
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
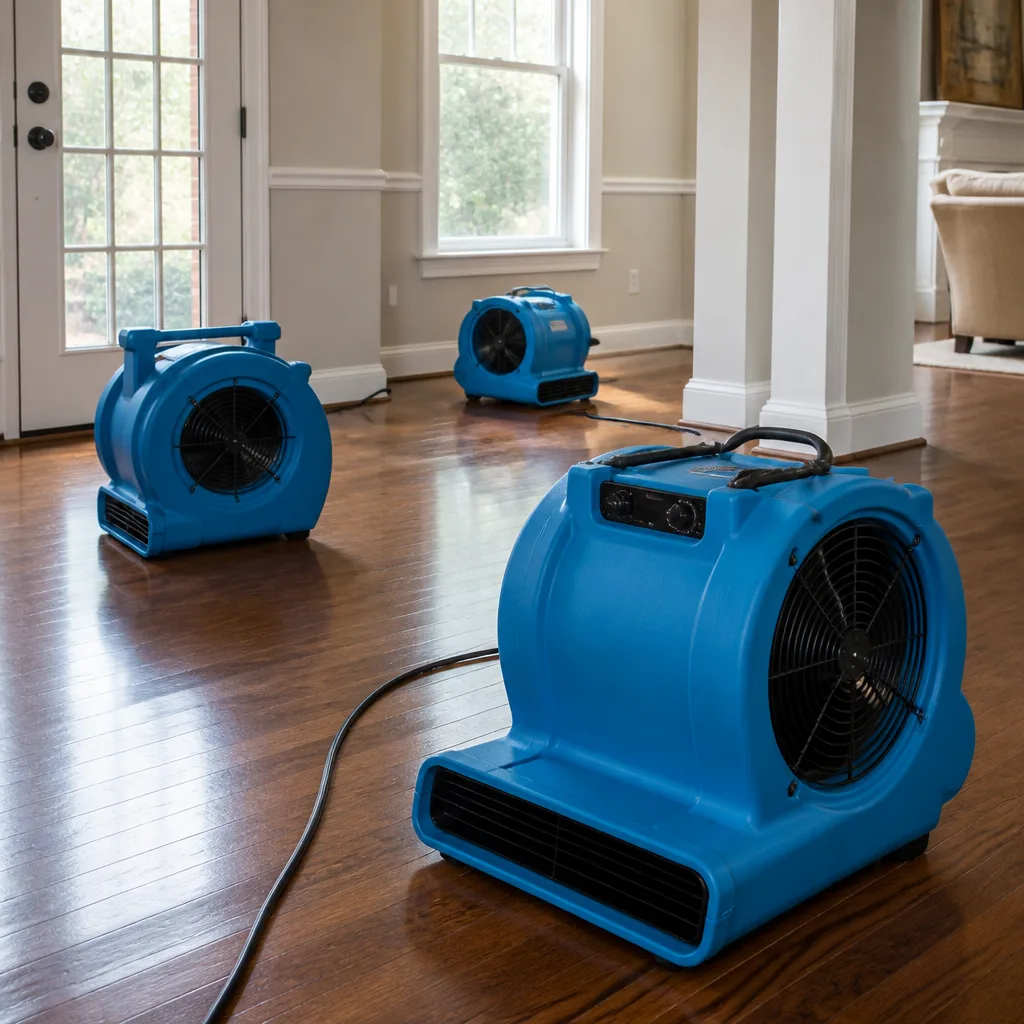
 Before
 After
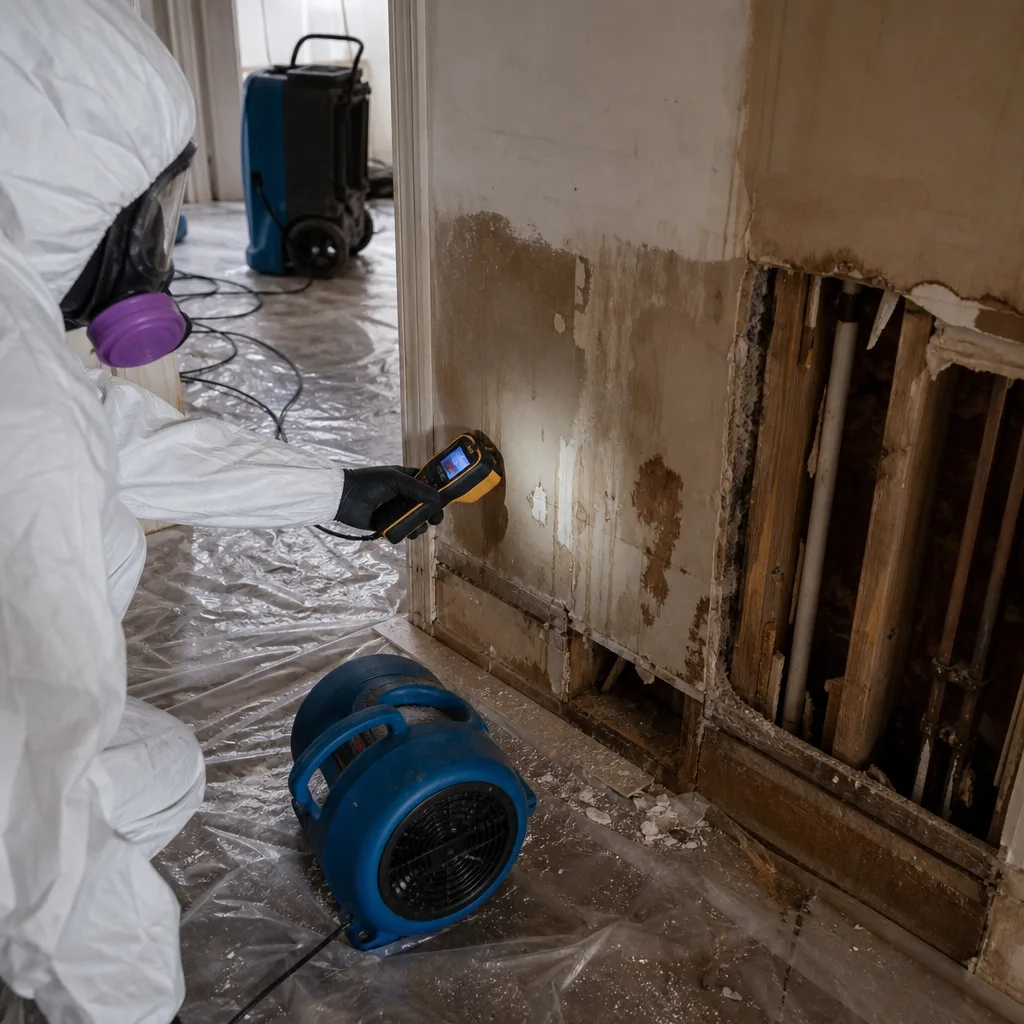 Before
 After
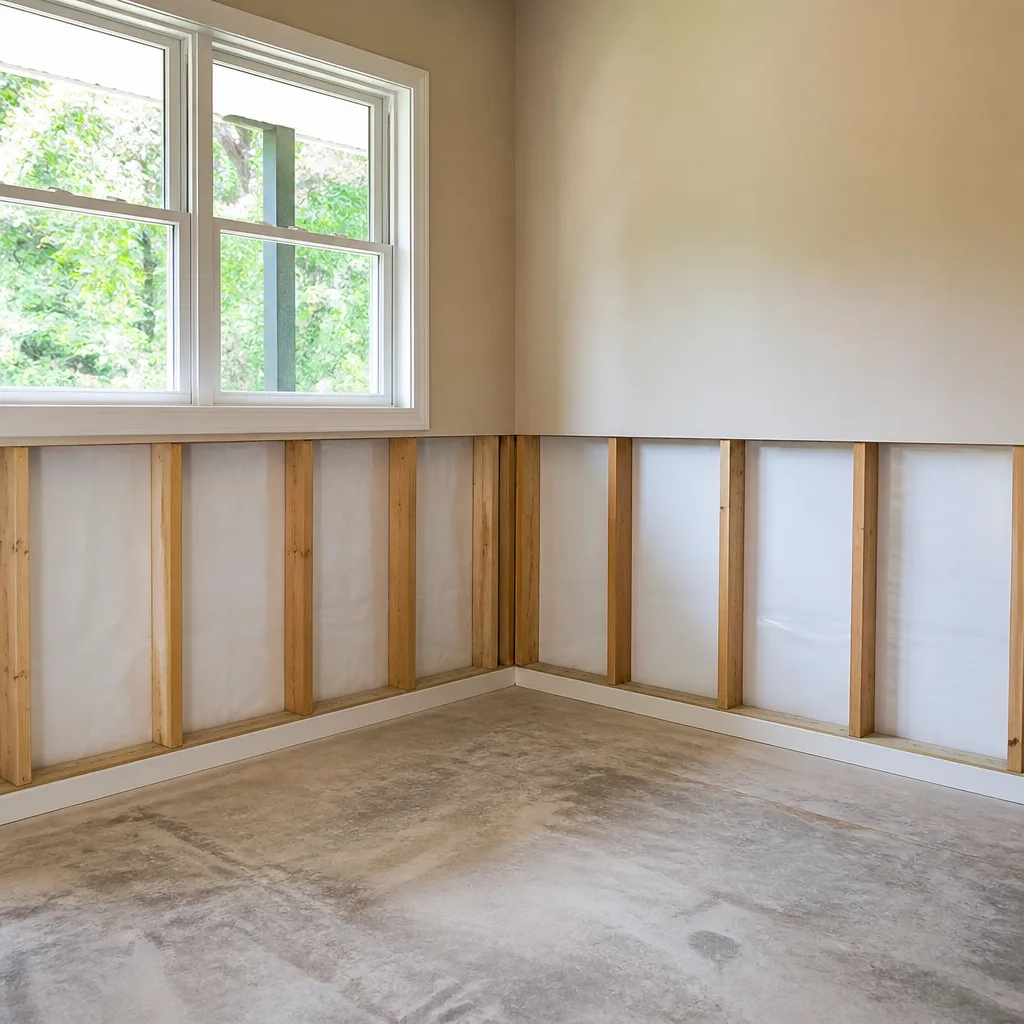
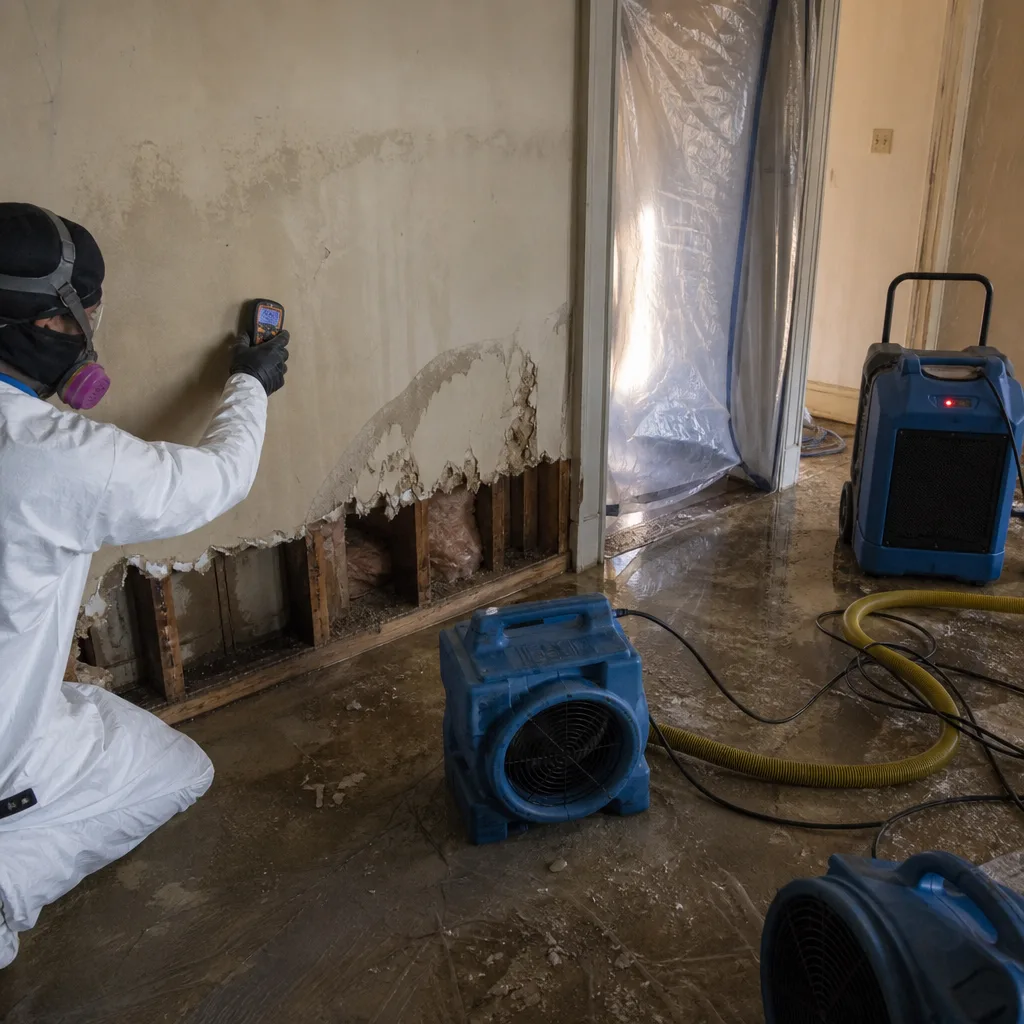 Before
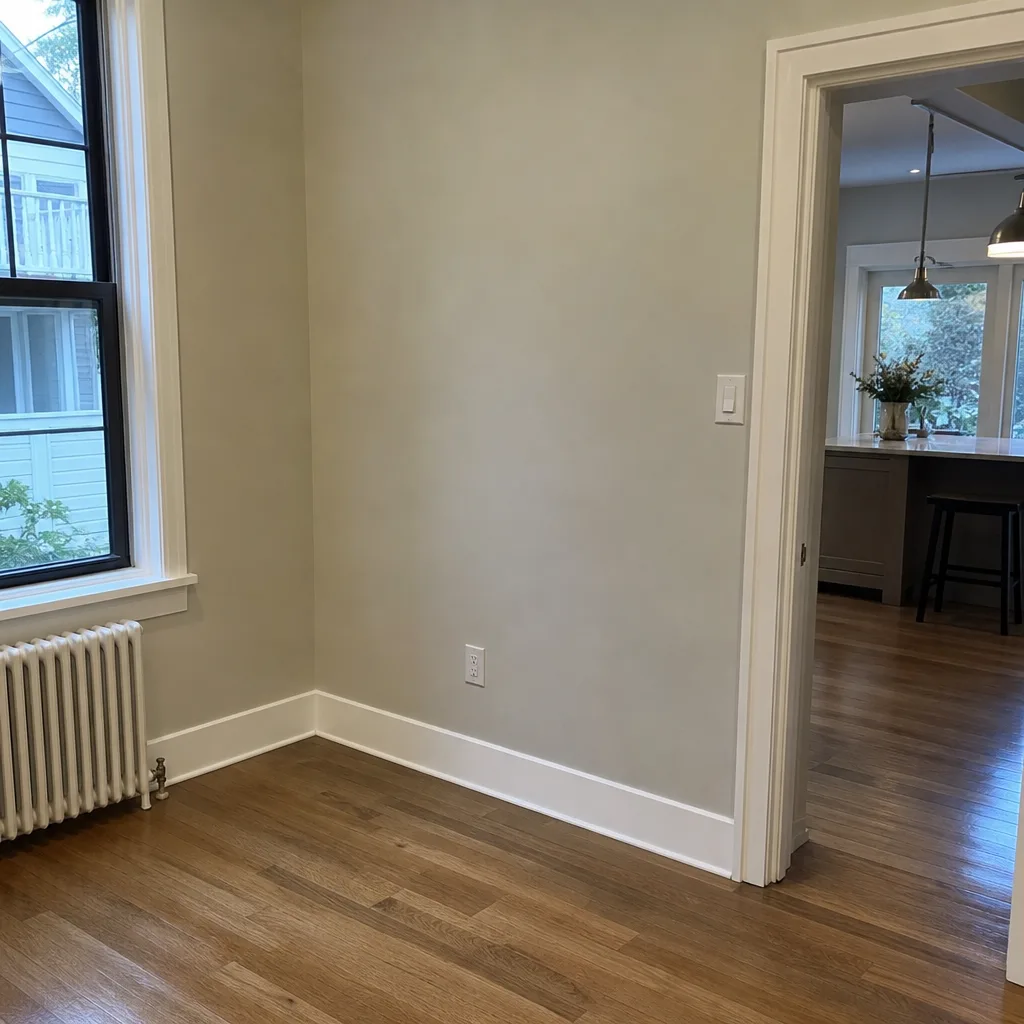 After
Does Insurance Cover Water Damage?
Whether your homeowner’s policy pays for water damage depends almost entirely on the cause and how well it’s documented. Sudden, accidental water events – a burst pipe, an appliance failure, an ice dam forcing water through the roof – are typically covered. Gradual leaks, flooding from outside your home, and damage that an adjuster can trace back to deferred maintenance usually are not.
That distinction sounds simple until you’re standing in four inches of water and an adjuster asks you to prove when the pipe failed, what the moisture readings were on arrival, and what was done in the first 48 hours. Most denied claims aren’t denied because the damage wasn’t real. They’re denied because the paperwork couldn’t support them. That’s the problem DryMark was built to solve – starting in 2011, when our founder Alicia Brennan was still on the other side of the desk, writing the denial letters.
Why It Happens
The Cause Was “Gradual” – or the Adjuster Says It Was
Insurance policies almost universally exclude water damage that developed slowly over weeks or months. A pinhole leak behind drywall that ran for three months before the ceiling buckled is the textbook example. If there’s staining, soft drywall, or mold behind the damaged area, an adjuster will argue the leak pre-existed the claim. What you can see: multiple layers of water staining with distinct tide marks, soft or discolored drywall that’s been compromised longer than a single event explains, and a musty smell that predates the visible damage.
The Water Came From Outside the Building
Standard homeowner’s policies exclude surface flooding – water that enters from the ground up during a storm or overland flow. This is one of the most common coverage gaps homeowners discover at the worst possible time. Flood coverage requires a separate NFIP or private flood policy. You can tell this is likely the cause if water entered through doors, window wells, or floor drains at or below grade, especially during a heavy rain event.
The Documentation Was Thin or Missing
A claim can be fully legitimate and still get reduced or denied if the restoration contractor didn’t produce daily moisture logs, room-by-room psychrometric readings, and dated photos from the first visit onward. Adjusters work from paper. If the paper isn’t there, the damage is effectively invisible to them. You’ll recognize this problem when you call your insurer and they ask for the drying logs – and the restoration company you used can’t produce them.
Maintenance Was Deferred – and It Shows
A water heater that fails at year 14 in a manufacturer’s 12-year rated unit is likely to be flagged as a maintenance issue. Same for a supply line with obvious corrosion at the fitting, or a sump pump that had no backup and failed during the first major storm in years. Adjusters are trained to look for visible signs of neglect. If the failed component was past its service life or showed prior deterioration, expect pushback on coverage regardless of how sudden the event felt.
What to Do Right Now
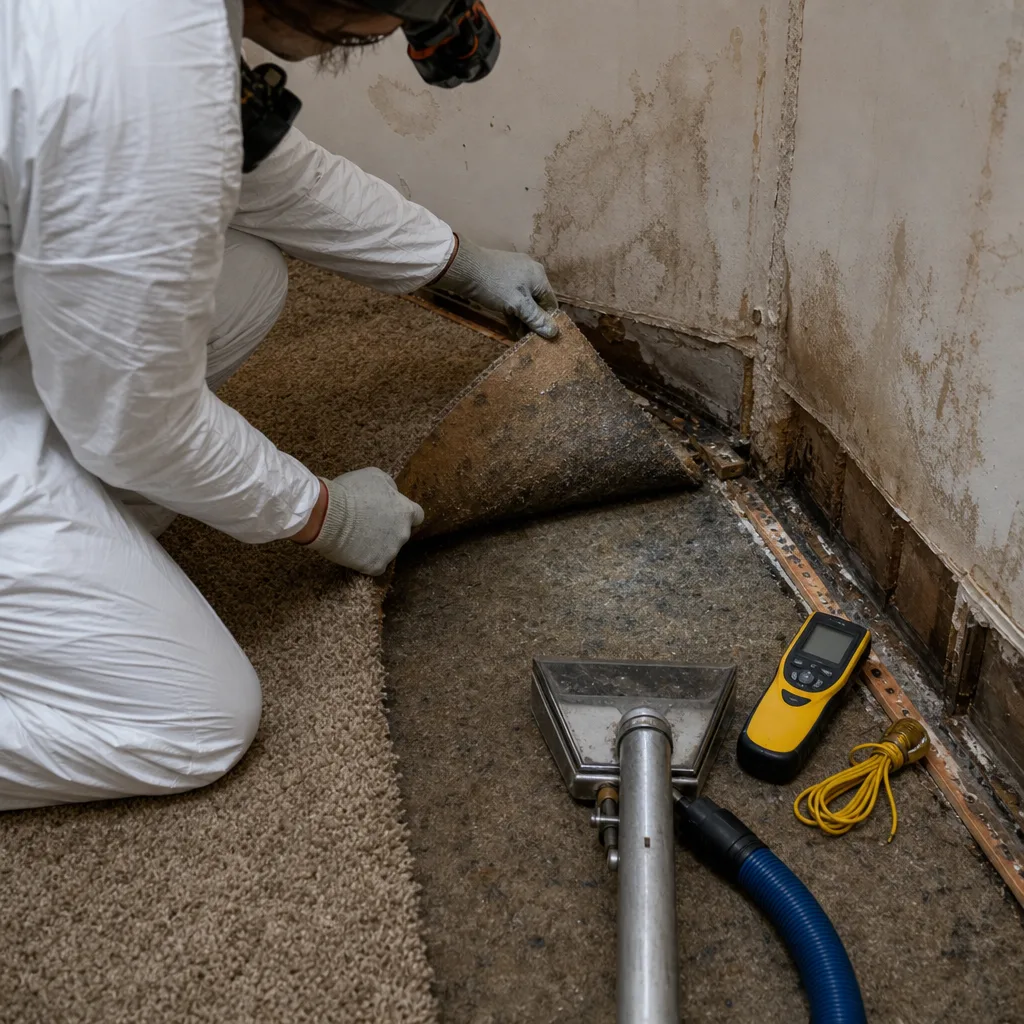
- Stop the water source if you can do it safely. Turn off the main water shutoff or the valve nearest the leak. If the shutoff is behind a flooded electrical panel or near any live wiring, do not touch it – call your utility and then call us. Water and live current together are not a DIY situation.
- Call your insurer to open a claim before cleanup begins. Document the call with the date, time, and the claim number they give you. Do not let anyone start removing material or drying equipment before the claim is open – premature cleanup is one of the most common reasons adjusters reduce payouts.
- Photograph everything before anything moves. Wide shots of every affected room, close-ups of the failure point, photos of standing water with something in frame for scale. If water is still moving, take video. The timestamp on your phone is part of the evidentiary record.
- Do not run fans, open windows, or try to dry it yourself yet. Uncontrolled drying can redistribute moisture into wall cavities and subfloor before a baseline moisture reading is established. That baseline is what the adjuster uses to determine scope. Without it, you’re negotiating without data.
- Write down everything you notice before anyone arrives. Where the water first appeared, what time you noticed it, whether there was a sound before the event, which rooms are affected. This becomes part of the claim narrative and can matter more than you’d expect.
BeforeAfterHow We Fix It
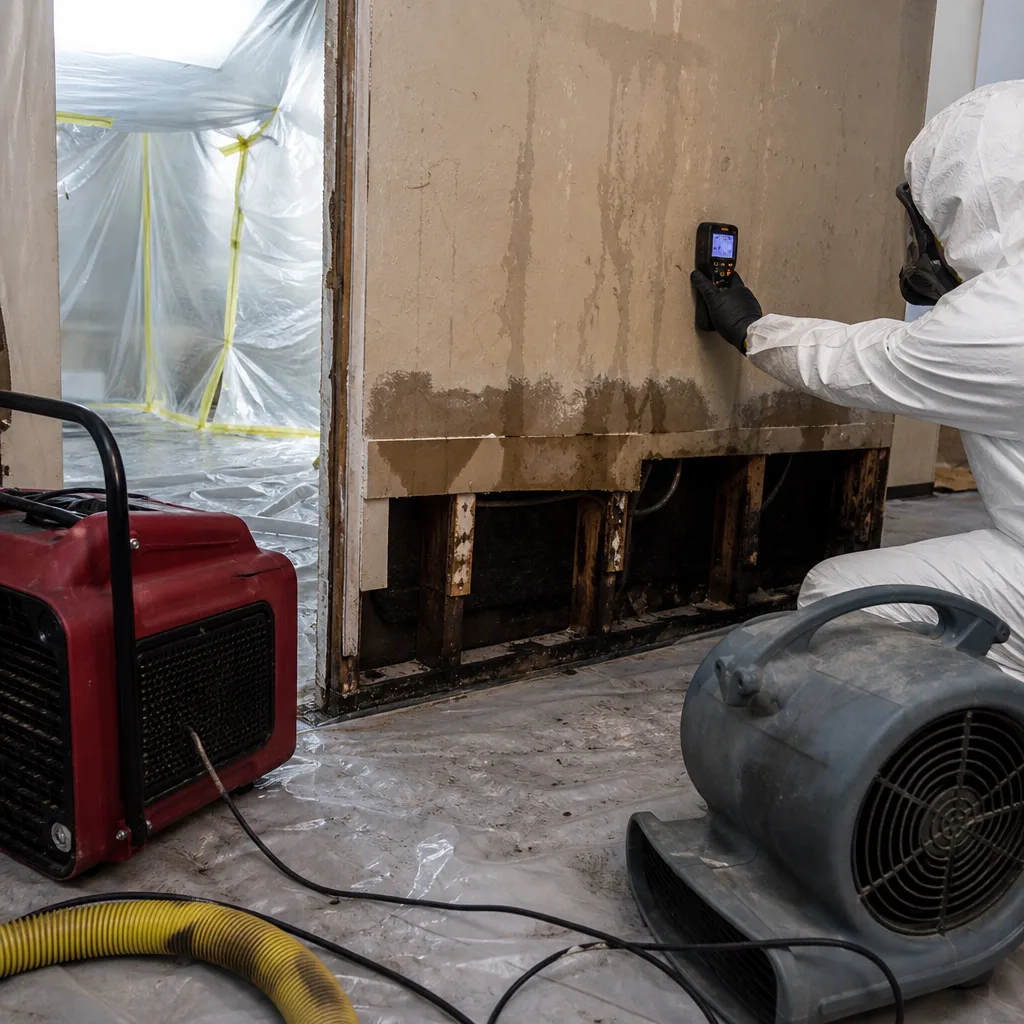
When your local DryMark Restoration team arrives, the first thing a technician does is establish a documented baseline – moisture readings in every affected room, room by room, logged by date and time. That’s not a courtesy; it’s the measurement that turns a restoration invoice into a claim a carrier will pay without a fight.
From there, the written scope is agreed before any equipment goes in. That’s Haven Standard, Clause 1: a flat written price, a defined scope, and no additions once the crew is inside. You’ll know exactly what’s happening and what it costs before anyone starts.
Drying equipment from Dri-Eaz, Phoenix, XPOWER, B-Air, and Injectidry goes in to bring structural moisture back to measurable dry – the condition the name describes. Daily readings continue until the numbers confirm it. Every visit is photographed. The documentation is documented to IICRC, RIA, and IFA standards and goes directly to your adjuster. Where damage requires rebuilding walls, flooring, or structural elements, Reconstruction is scoped and scheduled in writing as a separate phase.
The whole process is backed by the 365-Day Done Right Promise. If it’s not right, Alicia Brennan’s team makes it right. That’s in writing, not in the marketing copy.
Frequently Asked Questions
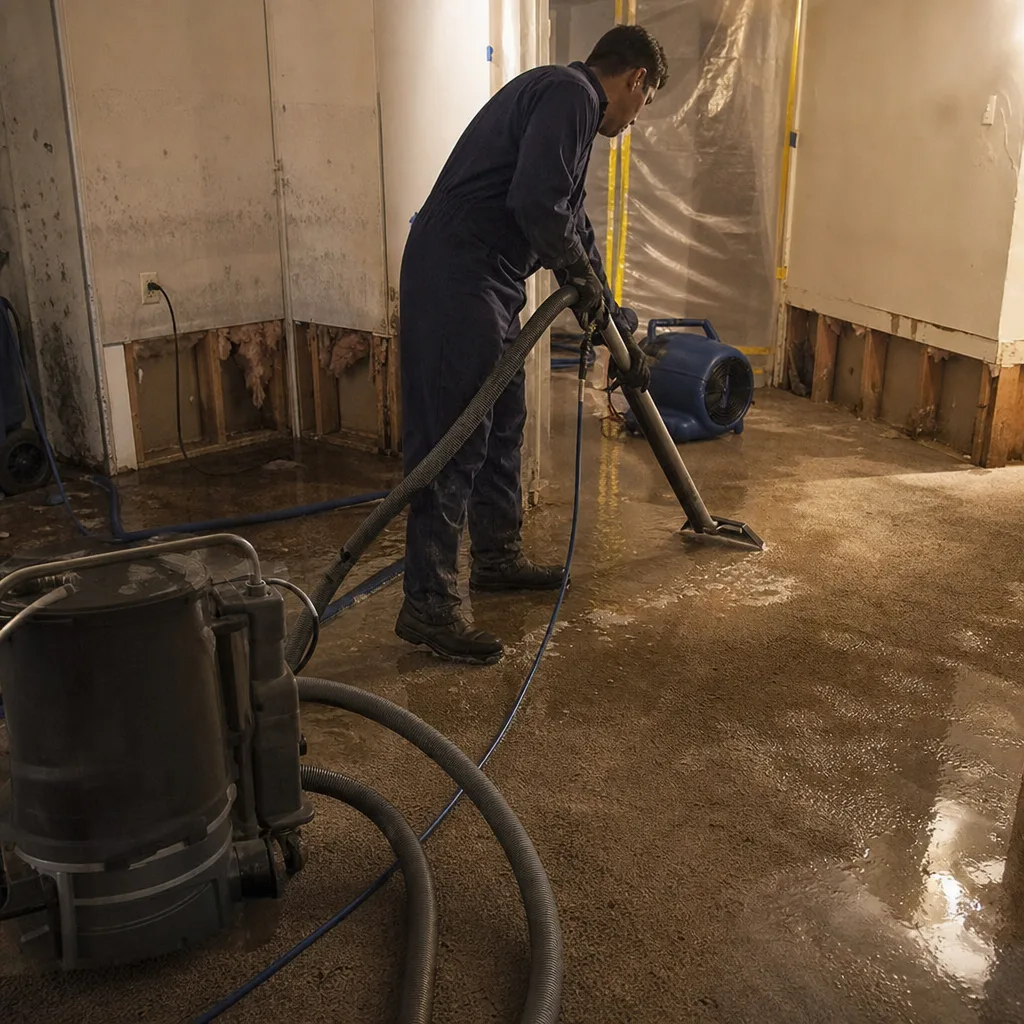
Yes, burst pipes are one of the most commonly covered water damage events under standard homeowner’s policies, provided the failure was sudden and accidental rather than the result of a pipe that showed obvious deterioration over time. Coverage typically includes the cost of drying, demolition, and rebuilding affected areas. What your policy may not cover is the pipe itself – structure and contents are usually covered; the source of the water often isn’t. Your local DryMark team produces the documentation your adjuster needs to process the claim cleanly, starting on the first visit.
This is where most claims run into trouble. If an adjuster can establish that the damage developed over weeks or months – based on staining patterns, mold growth, or the condition of structural materials – they will typically argue the damage was gradual and exclude it. The honest answer is: it depends on what the evidence shows. A thorough moisture assessment with documented readings gives you and your adjuster an accurate picture of what actually happened, which is the only defensible position either way. Call (629) 213-4606 and let your local DryMark team assess before you assume the worst.
Water damage does not pause. In most conditions, mold colonization becomes visible within 24 to 72 hours of a moisture event, and structural materials that stay wet longer than that – subfloor, wall framing, drywall – absorb progressively more damage the longer they sit. Beyond the physical damage, a delayed response gives an adjuster grounds to argue that the scope of the claim grew due to inaction rather than the original event. Call (629) 213-4606 now. A live person answers every call, around the clock, with no voicemail.
DryMark produces the documentation the adjuster needs and will coordinate directly with your insurance company. The daily moisture logs, the dated photo record, the written scope – these are standard deliverables on every job, not extras. Alicia Brennan’s team built the company around exactly this gap: restoration work that looks right to a homeowner but can’t be paid because the paperwork isn’t there. We close that gap. You can be as involved or as hands-off as you want; the paper trail exists either way. Call (629) 213-4606 to talk through how it works before any work begins.
Get It Fixed
Call (629) 213-4606 right now – a live person picks up, 24 hours a day, 7 days a week. Your local DryMark Restoration team will assess the damage, give you a written price before anything starts, and handle the documentation your insurer needs. No voicemail. No waiting until morning.
Written by Alicia Brennan, Owner at DryMark Restoration, serving homeowners nationwide since 2011.
What Our Customers Say
"Burst supply line upstairs. They had equipment in the house within a few hours and told me honestly which flooring could be saved and which could not."
- Jarrod P."They photographed behind the baseboards before removing anything. That documentation is the only reason the claim covered the wall cavity."
- Noreen S."Storm took part of the roof. They tarped it the same evening and the written scope came through the next morning."
- Emmett L.